Business
Mutual Fund and Elss
by yogini
3 chapters1.1 hr read
Chapter 1
Foundations of Mutual Funds
Why Invest? Understanding the Need for Investment
Imagine having ₹1 lakh in cash today. If you keep it under your mattress or in a regular savings account earning 3% interest annually, in ten years that amount will grow to about ₹1.34 lakh. But if the average inflation rate during that period is 6%, the same goods and services that cost ₹1 lakh today will cost ₹1.79 lakh in a decade. Your money, despite growing nominally, will actually buy less than it does now. This gap between the growth of your savings and the rising cost of living is why investing — not just saving — is essential for financial progress.
Why Invest? The Core Purpose
Investing means allocating money today with the expectation of generating returns in the future. It differs fundamentally from saving, which primarily involves setting aside money in low-risk, easily accessible instruments like savings accounts or fixed deposits. While saving protects capital, investing aims to grow it over time by accepting a degree of risk in exchange for the potential of higher returns.
Consider two individuals, both aged 30, who each set aside ₹10,000 every month. Priya keeps her money in a savings account yielding 3% post-tax interest. Arjun invests the same amount in a diversified equity mutual fund that historically delivers 10% annual returns. After 20 years, Priya’s savings grow to approximately ₹32.9 lakh. Arjun’s investment, assuming consistent returns, grows to about ₹75.9 lakh. The difference isn’t just in the absolute amount — it’s in what each sum can actually purchase in the future, adjusted for inflation.
This illustrates why investing is not optional for long-term goals like retirement, children’s education, or buying a home. Without returns that outpace inflation, the purchasing power of your money erodes silently over time. Investing bridges this gap by putting your capital to work in assets — such as stocks, bonds, or real estate — that have the potential to appreciate or generate income.
The Four Pillars of Investment Objectives
Investors pursue different goals depending on their life stage, financial situation, and aspirations. These objectives generally fall into four categories: wealth creation, income generation, capital preservation, and tax efficiency. Each serves a distinct purpose and often requires a different investment approach.
Wealth creation focuses on growing the principal amount over the long term. This is typical for goals like retirement or building a legacy, where the investor has a time horizon of 10 years or more and can tolerate short-term volatility. Equity-oriented investments, such as diversified mutual funds or index funds, are commonly used here because they offer higher growth potential over extended periods.
Income generation aims to produce regular cash flow from investments. Retirees relying on investment income to cover living expenses often prioritize this objective. Instruments like dividend-paying stocks, bond funds, or systematic withdrawal plans (SWPs) from mutual funds can provide steady payouts while aiming to preserve the underlying capital.
Capital preservation is about protecting the initial amount invested, especially when the goal is near-term or when the investor cannot afford to lose money. For example, someone saving for a down payment on a house in two years would prioritize safety over high returns. Liquid funds, short-term debt funds, or fixed deposits suit this objective due to their lower volatility and high liquidity.
Tax efficiency involves structuring investments to minimize tax liability legally. Certain instruments, like Equity Linked Savings Schemes (ELSS), offer dual benefits: potential for wealth creation and tax deductions under Section 80C of the Income Tax Act. By reducing taxable income, these investments effectively increase post-tax returns, making them valuable tools in a holistic financial plan.
These objectives are not mutually exclusive. A balanced portfolio might allocate portions to each — say, 60% to equity for wealth creation, 30% to debt for income and stability, and 10% to ELSS for tax savings — depending on individual needs.
Aligning Investments with Personal Goals
The first step in effective investing is clarity about what you want to achieve. Financial goals should be specific, measurable, time-bound, and realistic. Instead of vaguely wanting to “save for the future,” define it: “Accumulate ₹50 lakh for my child’s higher education in 15 years” or “Generate ₹40,000 per month in passive income after retirement at age 60.”
Once goals are defined, assess your risk tolerance — both your ability and willingness to withstand fluctuations in investment value. Ability depends on factors like income stability, emergency savings, and time horizon. A 25-year-old with a steady job and no dependents can typically take more risk than someone nearing retirement. Willingness, however, is psychological: some people lose sleep over a 10% market dip, while others view it as a buying opportunity.
A practical framework is to match your investment horizon with asset allocation. For goals less than three years away, prioritize capital preservation with debt or hybrid funds. For goals between three and seven years, a balanced approach — say, 40% equity and 60% debt — may suit moderate risk takers. For goals beyond seven years, especially retirement or wealth building, a higher equity allocation (60–80%) can harness compounding over time.
Take the example of Meera, a 35-year-old marketing professional earning ₹1.2 lakh monthly. She has three goals: build an emergency fund (₹3.6 lakh in 1 year), buy a car (₹8 lakh in 3 years), and retire comfortably (₹2 crore in 25 years). For the emergency fund, she chooses a liquid fund for safety and instant access. For the car, she opts for a short-term debt fund to avoid equity volatility. For retirement, she starts a monthly SIP of ₹15,000 in an equity-oriented hybrid fund, increasing it by 10% annually as her income grows. This alignment ensures each goal is served by an appropriate investment strategy.
From Awareness to Action: Starting Your Journey
Understanding the need to invest is only the beginning. The real value lies in translating awareness into disciplined action. Start by tracking your income and expenses to determine how much you can consistently set aside. Even ₹500 or ₹1,000 per month is a meaningful beginning — what matters is the habit.
Next, match your savings to your goals using the framework above. Open a systematic investment plan (SIP) in a mutual fund that aligns with your objective and risk profile. Automate the process so investments happen on a fixed date each month, removing the need to time the market or rely on motivation.
Review your portfolio annually — not to chase returns, but to ensure it still reflects your goals and risk tolerance. Life changes: a promotion, a marriage, or a child’s birth may shift your priorities. Adjust your allocations accordingly, but avoid frequent tinkering based on short-term market movements.
Remember, investing is not about achieving perfection. It’s about making informed, consistent decisions that compound over time. The earlier you start, the more you benefit from the power of compounding — where returns generate their own returns. A monthly SIP of ₹5,000 starting at age 25, assuming 10% annual returns, can grow to over ₹1.5 crore by age 60. Start ten years later, and the same effort yields roughly ₹55 lakh. The difference isn’t just in the amount — it’s in the freedom, security, and options that financial preparedness provides.
By recognizing inflation’s silent toll, clarifying your objectives, aligning investments with your life, and acting with discipline, you transform money from a passive store of value into an active tool for building the future you want. This foundation — understanding why to invest — is what makes the rest of the journey meaningful and effective.
What Is a Mutual Fund? Definition and Structure
A mutual fund is a pooled investment vehicle that collects money from multiple investors and invests it in a diversified portfolio of stocks, bonds, or other securities. When you invest in a mutual fund, you buy units that represent your proportional share of the fund’s holdings. This structure allows individual investors to access professional management and diversification that would be difficult or costly to achieve on their own.
The core idea is simple: by pooling resources, investors gain exposure to a broad range of assets, reducing the risk associated with putting all money into a single security. For example, instead of buying shares of just one company, a mutual fund might hold dozens or even hundreds of stocks across sectors like technology, healthcare, and finance. If one company underperforms, the impact on the overall portfolio is limited.
Mutual funds are managed by professional fund managers who make investment decisions based on the fund’s stated objective — whether it’s growth, income, or capital preservation. Investors benefit from this expertise without needing to monitor markets daily. Returns come in two forms: capital appreciation (increase in the value of the fund’s holdings) and income (dividends or interest earned by the portfolio). These are reflected in the fund’s Net Asset Value (NAV), which we’ll explore shortly.
The Three-Tier Structure of Mutual Funds in India
In India, mutual funds operate under a strict three-tier structure designed to protect investor interests. This model separates ownership, oversight, and management to ensure transparency and accountability.
The sponsor is the entity that establishes the mutual fund. Think of the sponsor as the founder — they initiate the fund and contribute a minimum of 40% of the net worth of the Asset Management Company (AMC). The sponsor must meet eligibility criteria set by SEBI, including a track record of financial integrity and profitability. For instance, if a bank like SBI wants to launch a mutual fund, it acts as the sponsor and promotes the creation of SBI Mutual Fund.
The trustee acts as the guardian of investors’ money. Appointed by the sponsor but operating independently, the trustee ensures that the fund is managed according to the Securities and Exchange Board of India (Mutual Funds) Regulations, 1996, and the fund’s own offer document. The trustee does not manage investments directly but oversees the AMC’s activities, reviews compliance, and can take corrective action if rules are violated. For example, if the AMC tries to invest in a sector beyond the fund’s mandate, the trustee can block it. Trustees are typically individuals or trust companies with expertise in finance and governance.
The Asset Management Company (AMC) is the engine of the mutual fund. It is responsible for launching schemes, managing portfolios, handling investor transactions, and providing customer service. The AMC employs fund managers, analysts, and operations teams to make day-to-day investment decisions. It earns a fee — usually a percentage of assets under management — for its services. In our earlier example, SBI Funds Management Private Limited is the AMC that runs SBI Mutual Fund schemes.
This separation creates checks and balances: the sponsor provides capital and brand support, the trustee ensures compliance and investor protection, and the AMC handles execution. If any tier fails in its duty, the others can intervene. For instance, if the AMC engages in excessive risk-taking, the trustee can report it to SEBI or even terminate the AMC’s appointment.
Role of SEBI in Regulating Mutual Funds
The Securities and Exchange Board of India (SEBI) is the primary regulator of mutual funds in India. Established in 1992 and given statutory powers in 1995, SEBI’s mandate includes protecting investor interests, promoting fair and transparent markets, and regulating securities intermediaries — including mutual funds.
SEBI regulates every aspect of a mutual fund’s lifecycle. Before a fund house can launch a new scheme, it must submit detailed documentation to SEBI for approval, including the investment objective, asset allocation, risk factors, and fee structure. SEBI reviews this to ensure clarity and prevent misleading claims. For example, if an AMC wants to market a fund as “low risk,” SEBI will scrutinize the underlying portfolio to verify that the claim aligns with actual holdings.
SEBI also sets limits on expenses. Mutual funds can charge an expense ratio — the annual fee covering management, administration, and distribution costs — but SEBI caps this based on the fund’s size and type. Equity funds, for instance, have a higher allowable expense ratio than debt funds due to higher research and trading costs. As of recent regulations, the maximum expense ratio for an equity fund with ₹500 crore in assets is 2.25%, decreasing as assets grow. This prevents excessive fees from eroding investor returns.
Transparency is another key focus. SEBI mandates daily disclosure of NAV, monthly portfolio holdings, and quarterly expense ratios. Fund houses must also label schemes by risk level using a standardized “riskometer” — ranging from low to high — so investors can quickly assess suitability. If a fund’s risk profile changes significantly, the AMC must inform investors and may need to re-label the scheme.
In cases of misconduct, SEBI has enforcement powers. It can impose fines, restrict new scheme launches, or even bar individuals from participating in the securities market. For example, in 2021, SEBI penalized an AMC for front-running — where dealers traded ahead of client orders — demonstrating that regulatory oversight extends to ethical conduct.
This regulatory framework ensures that mutual funds operate with integrity, giving retail investors confidence that their money is managed responsibly.
How Net Asset Value (NAV) Is Calculated and Used
The Net Asset Value (NAV) is the price at which you buy or sell units of a mutual fund. It represents the per-unit market value of the fund’s assets minus liabilities, calculated at the end of each trading day.
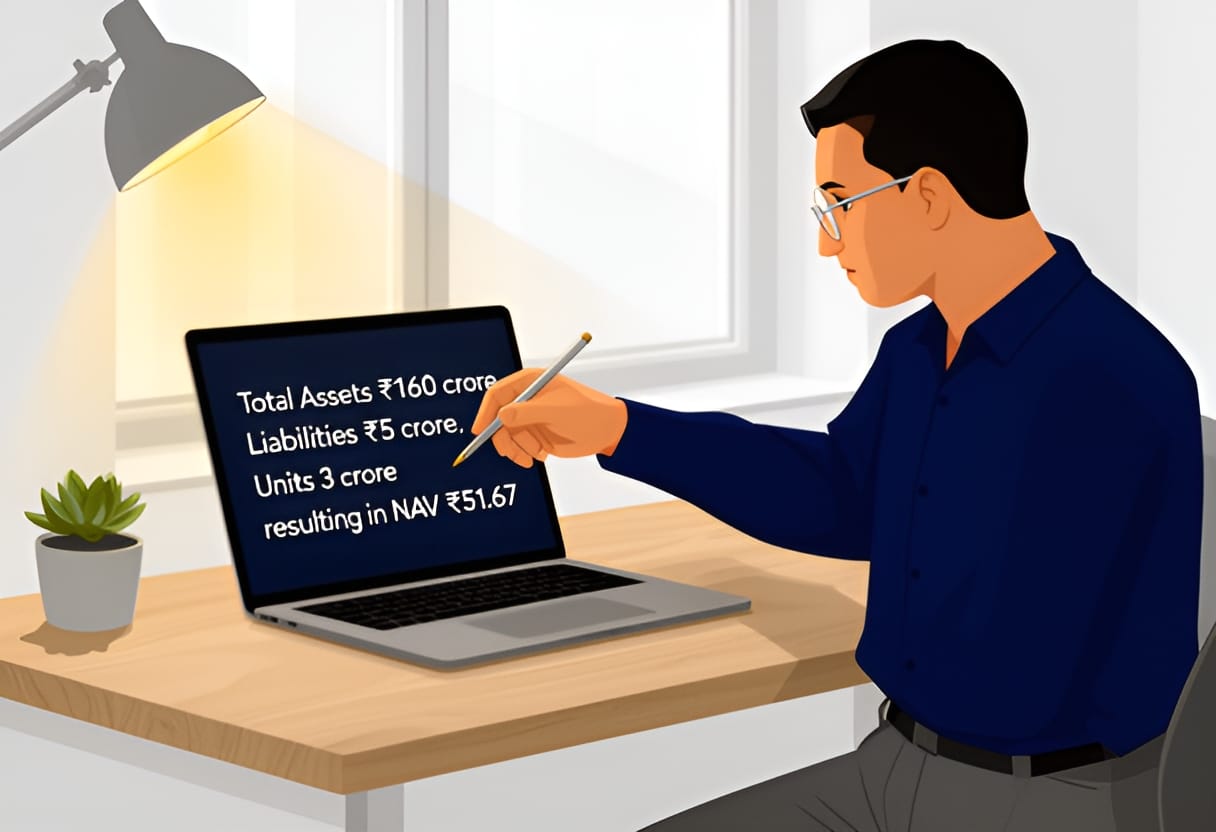
The formula is straightforward: NAV = (Total Value of Assets – Total Liabilities) / Number of Outstanding Units
Assets include the market value of all securities held (stocks, bonds, etc.), cash, and accrued income. Liabilities cover expenses like management fees, pending payments, and other obligations. The result is divided by the total number of units issued to investors.
For example, suppose a mutual fund holds stocks worth ₹100 crore, bonds worth ₹50 crore, and ₹10 crore in cash. Its total assets are ₹160 crore. If it has ₹5 crore in liabilities (such as unpaid fees), the net assets are ₹155 crore. If the fund has issued 10 crore units, the NAV is ₹15.50 (₹155 crore ÷ 10 crore units).
NAV is calculated after the market closes, using closing prices of securities. You cannot buy or sell units at intraday prices; all transactions during the day are processed at the next day’s NAV. This is different from stocks, where prices fluctuate continuously.
It’s important to understand that NAV alone doesn’t indicate whether a fund is “cheap” or “expensive.” A fund with an NAV of ₹10 isn’t inherently better than one with an NAV of ₹500. What matters is the percentage change in NAV over time, which reflects the fund’s return. If Fund A’s NAV rises from ₹100 to ₹110 in a year, it delivered a 10% return — the same as Fund B rising from ₹10 to ₹11.
NAV also determines how many units you receive when you invest. If you contribute ₹10,000 to a fund with an NAV of ₹50, you get 200 units (₹10,000 ÷ ₹50). When you redeem, the number of units multiplied by the current NAV gives you the redemption amount.
Consider Meera, who starts a monthly SIP of ₹5,000 in an equity fund. In Month 1, the NAV is ₹25, so she buys 200 units. In Month 2, the market dips and NAV falls to ₹20 — her ₹5,000 buys 250 units. In Month 3, NAV rises to ₹30, giving her 166.67 units. Over time, this averaging effect — known as rupee-cost averaging — reduces the impact of volatility. When she checks her statement, her total units multiplied by the current NAV show her investment’s value.
NAV is also used to calculate returns. If her NAV grows from an average cost of ₹22 to ₹30 over a year, her approximate return is (30–22)/22 = 36.4%. This makes NAV the central metric for tracking performance, comparing funds, and making informed decisions about when to invest or redeem.
By understanding NAV, you see how mutual funds translate underlying asset value into a transparent, accessible price — enabling you to participate in professional portfolio management with clarity and confidence.
Types of Mutual Funds: By Asset Class and Investment Objective
Mutual funds are broadly categorized based on the type of securities they invest in and the goals they aim to achieve. Understanding these classifications helps you align your investments with your risk tolerance, time horizon, and financial objectives. This section breaks down mutual funds by asset class and investment objective, using real-world examples to clarify how each type functions and who it suits best.
Equity Funds: Growth Through Stock Market Exposure
Equity funds primarily invest in company stocks, aiming for capital appreciation over the long term. Since stock prices fluctuate based on company performance, economic conditions, and market sentiment, these funds carry higher risk but also offer the potential for higher returns compared to other fund types.
Equity funds are further divided based on market capitalization, investment style, or sector focus. For example:
- Large-cap funds invest in the top 100 companies by market capitalization (e.g., Reliance Industries, TCS, HDFC Bank). These tend to be less volatile and suitable for investors seeking steady growth with moderate risk.
- Mid-cap and small-cap funds target emerging companies with higher growth potential but greater price swings. A small-cap fund might invest in companies like Page Industries or Astral Ltd., offering higher return potential over 7–10 years, albeit with increased short-term volatility.
- Sectoral or thematic funds concentrate on specific industries such as banking, technology, or healthcare. A banking fund, for instance, would have most of its assets in stocks like ICICI Bank, State Bank of India, and Kotak Mahindra Bank. While these can deliver strong returns when the sector performs well, they lack diversification and are riskier if the sector faces headwinds.
- Flexi-cap funds have the freedom to invest across market caps, adjusting allocations based on market conditions. This adaptability allows fund managers to shift toward large caps during uncertainty and small caps during rallies.
For example, if you invest ₹1 lakh in a large-cap equity fund with an average annual return of 12% over 10 years, your investment could grow to approximately ₹3.1 lakh, assuming compounding. However, returns are not guaranteed — during a market downturn, the NAV could drop by 20–30% in a short period. This makes equity funds best suited for long-term goals like retirement or a child’s education, where you can stay invested for at least five to seven years to ride out volatility.
Debt Funds: Stability and Regular Income
Debt funds invest in fixed-income instruments such as government bonds, corporate debentures, treasury bills, and money market securities. Their primary objective is to generate regular income while preserving capital, making them less volatile than equity funds.
Returns in debt funds come mainly from interest payments and changes in bond prices due to interest rate movements. When RBI lowers interest rates, existing bonds with higher coupon rates become more valuable, potentially increasing the fund’s NAV. Conversely, rising rates can reduce NAV.
Debt funds are classified by maturity and credit quality:
- Liquid funds invest in instruments with maturities of up to 91 days (e.g., treasury bills, commercial paper). They offer high liquidity and are often used as a savings account alternative. For instance, parking ₹5 lakh in a liquid fund yielding 6.5% annually could generate around ₹270 per month in returns, with the ability to redeem within one business day.
- Ultra-short duration funds hold securities maturing in 3–6 months, slightly increasing yield potential while maintaining low volatility.
- Corporate bond funds allocate at least 80% to high-rated corporate bonds, offering better returns than government securities but with modest credit risk. A fund holding bonds from companies like Tata Motors or NTPC might yield 7–8% annually.
- Credit risk funds lend to lower-rated companies to earn higher interest, increasing both potential returns and default risk. These are suitable only for investors who understand and can tolerate credit events.
For example, if you invest ₹2 lakh in a corporate bond fund with an average yield of 7.5%, you might expect around ₹15,000 in annual income. If interest rates fall during your holding period, the NAV could rise, adding to your total return. Debt funds are ideal for short-term goals (1–3 years), emergency funds, or as a stabilizing component in a diversified portfolio.
Hybrid Funds: Balancing Growth and Stability
Hybrid funds, also known as balanced funds, invest in both equity and debt instruments to offer a middle path between growth and stability. The equity portion aims for capital appreciation, while the debt component reduces volatility and provides income.
The allocation between equity and debt varies by fund type:
- Aggressive hybrid funds typically hold 65–80% in equities and the rest in debt. These suit investors with a moderate to high risk appetite seeking growth with some downside protection.
- Conservative hybrid funds allocate 10–25% to equities and the rest to debt, prioritizing capital preservation with modest growth potential.
- Dynamic asset allocation funds (or balanced advantage funds) adjust their equity-debt mix based on market valuations. When stocks are expensive, they shift toward debt; when valuations are attractive, they increase equity exposure. This automatic rebalancing helps manage risk without requiring investor intervention.
For instance, an aggressive hybrid fund might invest 70% in stocks like Infosys and Hindustan Unilever, and 30% in government and corporate bonds. If the stock market rises 10% in a year and bonds yield 6%, the fund could deliver approximately 8.5–9% returns, depending on exact weighting. During a market correction, the debt portion may cushion losses, limiting NAV decline to 5–8% compared to a potential 15–20% drop in a pure equity fund.
Consider Arjun, who wants to save for a home down payment in five years. He chooses an aggressive hybrid fund with a historical return of 9% post-tax. By investing ₹15,000 monthly via SIP, he could accumulate roughly ₹11 lakh in five years — enough for a 20% down payment on a ₹55 lakh property. The hybrid structure helps him pursue growth while reducing the risk of a major equity market crash derailing his plan.
Funds by Investment Objective: Matching Strategy to Purpose
Beyond asset class, mutual funds are also grouped by their primary investment goal. This classification helps you pick funds based on what you’re trying to achieve — whether it’s long-term wealth, regular income, quick access to cash, or tax savings.
- Growth funds focus on capital appreciation and are predominantly equity-oriented. They reinvest dividends and aim to grow the NAV over time. Ideal for goals 5+ years away, such as building a retirement corpus.
- Income funds prioritize regular returns and are mainly debt-based. They aim to deliver steady payouts through dividends or interest, suitable for retirees or those seeking supplemental income.
- Liquidity funds emphasize safety and instant access. These are ultra-short-term debt funds with minimal NAV fluctuation, often used to park surplus cash or emergency funds. For example, Meera keeps ₹3 lakh in a liquid fund to cover unexpected medical expenses, earning ~5.5% post-tax while being able to withdraw anytime.
- ELSS (Equity Linked Savings Scheme) funds are a special category of equity funds that offer tax benefits under Section 80C of the Income Tax Act. They have a mandatory three-year lock-in period — the shortest among all 80C options — and invest predominantly in stocks. Because they are equity-linked, returns are market-dependent but historically strong over the long term.
For example, if you invest ₹1.5 lakh in an ELSS fund (the maximum deductible under Section 80C) and fall in the 30% tax bracket, you save ₹46,500 in taxes annually (including cess). Assuming a 10% annual return over 10 years, your investment could grow to approximately ₹2.55 lakh. After the three-year lock-in, you can choose to stay invested or redeem — unlike PPF or NSC, which have longer fixed terms.
ELSS funds come in variants: some focus on large caps for stability, others on flexi-cap or thematic strategies for higher growth. A salaried professional like Priya might start a monthly SIP of ₹12,500 in an ELSS fund to utilize her full ₹1.5 lakh 80C limit, benefit from rupee-cost averaging, and build a tax-efficient equity portfolio over time.
Matching Fund Types to Your Goals and Horizon
Choosing the right fund type depends on your investment horizon, risk tolerance, and financial objective. The table below summarizes how different fund categories align with common investor profiles:
| Fund Type | Typical Horizon | Risk Level | Best Suited For | Example Goal |
|---|---|---|---|---|
| Liquid / Ultra-short debt | 0–1 year | Low | Emergency fund, short-term parking | Holding bonus before a vacation |
| Corporate bond / Banking & PSU debt | 1–3 years | Low to moderate | Income, capital preservation | Saving for a car down payment |
| Conservative hybrid | 3–5 years | Moderate | Balanced growth with lower volatility | Child’s school fees in 4 years |
| Aggressive hybrid / Flexi-cap equity | 5+ years | Moderate to high | Wealth creation, long-term growth | Retirement corpus at age 60 |
| ELSS (equity-linked tax saver) | 5+ years (post lock-in) | High | Tax saving + long-term wealth | Reducing taxable income while building assets |
| Sectoral / Thematic equity | 7+ years | High | Conviction-based bets | Betting on renewable energy over a decade |
For instance, if you’re saving for a wedding in 18 months, a liquid or ultra-short duration fund makes sense — you prioritize capital safety and easy access over high returns. If you’re 30 years old and planning for retirement at 60, allocating 70–80% of your long-term savings to equity or hybrid funds allows compounding to work over decades, with the option to shift to debt as you near your goal.
It’s also wise to review your allocations annually. As goals approach, gradually reducing equity exposure — known as glide-path investing — helps protect accumulated gains. For example, someone who started with 80% equity at age 25 might shift to 50% equity by 45 and 30% by 55, ensuring the portfolio evolves with changing needs.
By understanding how mutual funds are classified and what each type aims to achieve, you can move beyond random investing and build a purpose-driven portfolio. The next step is to look at how these funds have evolved in India — from a single player to a diverse, competitive industry offering choices for every kind of investor.
History and Evolution of Mutual Funds in India
The concept of pooling money from multiple investors to invest in a diversified portfolio traces back to 1924 in the United States, when the Massachusetts Investors Trust launched what is widely regarded as the first modern mutual fund. This innovation allowed individuals with modest savings to access professional money management and diversification — previously available only to the wealthy. The fund issued redeemable shares, published a net asset value, and operated under a clear investment objective, setting a template that would later spread globally.
In India, the journey began four decades later with the establishment of the Unit Trust of India (UTI) in 1963 through an Act of Parliament. UTI was created as a public sector initiative to encourage small savings and channel them into productive investments, particularly to support industrial growth. Its first scheme, Unit Scheme 1964 (US-64), offered investors a way to participate in equity markets through a structured, regulated vehicle. For the next three decades, UTI operated as the sole mutual fund in the country, enjoying a monopoly that allowed it to build trust and awareness among retail investors, especially in semi-urban and rural areas.
Phase One: The UTI Monopoly (1963–1987)
During this period, UTI focused on promoting the idea of mutual funds as a safe, accessible route to market-linked returns. It launched simple, dividend-oriented schemes and relied heavily on a network of agents and post offices to reach investors. The regulatory framework was minimal, with oversight shared between the Reserve Bank of India (RBI) and the Ministry of Finance. While UTI played a crucial role in popularizing the concept, the lack of competition meant limited innovation in product design or fee structure. Returns were often modest, and transparency — such as regular NAV disclosure or portfolio reporting — was inconsistent.
A key limitation of this era was the absence of investor choice. With only one provider, individuals could not compare performance, expenses, or risk profiles. Moreover, UTI’s close ties to government objectives sometimes led to investments driven by policy rather than pure financial merit, which affected long-term returns in certain schemes.
Phase Two: Public Sector Entry (1987–1993)
The first significant shift came in 1987 when public sector banks and insurance companies were permitted to sponsor mutual funds. The State Bank of India launched SBI Mutual Fund in June 1987, followed by Canbank Mutual Fund (later Canara Robeco), LIC Mutual Fund, and others. This marked the beginning of competition, though the landscape remained dominated by state-backed entities.
These new entrants brought greater marketing muscle and distribution reach, leveraging their extensive branch networks. Fund offerings began to diversify beyond UTI’s traditional models, introducing schemes with different maturities and asset allocations. However, regulation still lagged. There were no uniform standards for accounting, disclosure, or investor protection, leading to inconsistencies in how funds reported performance or managed risk.
Despite these shortcomings, the public sector phase expanded the investor base significantly. By the early 1990s, assets under management (AUM) had grown from under ₹1,000 crore in the UTI era to over ₹47,000 crore across all public and UTI funds. More importantly, the idea that mutual funds could be offered by multiple trusted institutions began to take root, setting the stage for broader liberalization.
Phase Three: Private Sector and Regulatory Reforms (Post-1993)
The real transformation began in 1993, when the Securities and Exchange Board of India (SEBI) was empowered to regulate mutual funds and private sector players were allowed to enter the market. This marked the start of the third and most dynamic phase of evolution.
SEBI introduced the Mutual Fund Regulations in 1993, which established a uniform legal framework for all fund houses, regardless of ownership. Key provisions included:
- Clear definition of the three-tier structure (sponsor, trustee, AMC)
- Mandatory SEBI approval for new fund launches
- Requirements for disclosure of portfolio holdings, NAV, and expense ratios
- Limits on expense ratios and restrictions on risky investments
These rules brought much-needed transparency and accountability. For the first time, investors could compare funds on a level playing field — knowing exactly what they were paying in fees and what securities the fund held.
The entry of private sector fund houses — such as Kothari Pioneer (now Franklin Templeton), DSP Merrill Lynch (now DSP Mutual Fund), and later HDFC, ICICI Prudential, and Axis — intensified competition. Innovation accelerated: new fund offerings emerged, including sectoral schemes, index funds, and systematic investment plans (SIPs). AMCs began investing in research, technology, and investor education.
Further regulatory upgrades followed:
- 1996 Regulations: Introduced stricter norms on related-party transactions, independent trustees, and valuation of securities.
- 2002 Regulations: Replaced the 1993 framework with a more comprehensive code, aligning with global best practices. It emphasized risk management, portfolio diversification, and independent custodianship.
- 2016 Updates: Focused on liquidity risk management, stress testing, and side-pocketing mechanisms for troubled assets, especially in debt funds. Also enhanced disclosure requirements for fund performance and risk ratios.
These reforms have been instrumental in building investor confidence. Today, SEBI mandates daily NAV publication, monthly portfolio disclosures, and quarterly expense ratio reporting — all accessible through fund websites and platforms like the Association of Mutual Funds in India (AMFI).
Current Landscape: Scale and Participation
As of March 2024, the Indian mutual fund industry manages over ₹50 lakh crore in AUM — a remarkable increase from the ₹47,000 crore recorded in 1993. This growth has been driven by rising financial literacy, the proliferation of SIPs, and strong equity market performance over the past decade.
Investor base expansion has been equally striking. The number of folios (accounts) has surpassed 18 crore, with SIP accounts alone exceeding 8 crore. Notably, retail participation has shifted from urban centers to Tier 2 and Tier 3 cities, aided by digital platforms, vernacular content, and simplified KYC processes.
ELSS funds, introduced in 2005, have become a significant part of this ecosystem. With over ₹2.5 lakh crore in AUM as of early 2024, they remain one of the most popular Section 80C instruments, particularly among salaried individuals seeking both tax savings and equity exposure.
For instance, consider Arjun, a 32-year-old software engineer in Bengaluru. He started a monthly SIP of ₹10,000 in an ELSS fund in 2020, primarily to save tax under Section 80C. Over four years, his total investment of ₹4.8 lakh has grown to approximately ₹7.9 lakh (assuming an average annual return of 13%). Beyond the tax savings of up to ₹46,500 per year, he has benefited from rupee-cost averaging and long-term wealth creation — all within a regulated, transparent structure made possible by decades of regulatory evolution.
Try This
This week, take three steps to connect with the evolution you’ve just learned about:
- Visit the AMFI website (www.amfiindia.com) and check the current industry AUM and number of folios — note how they’ve changed from the figures mentioned above.
- Open the factsheet of any ELSS fund (e.g., from Axis, SBI, or Mirae Asset) and locate the portfolio disclosure, expense ratio, and NAV history — observe how SEBI’s regulations enable this transparency.
- Reflect on your own investment horizon: if you’re saving for a goal 10+ years away, how might an equity-oriented fund like an ELSS fit into your strategy, given its historical role in wealth creation?
Key Takeaways
- Mutual funds originated in the USA in 1924 as a way to democratize access to professional investing; India’s journey began with UTI’s establishment in 1963.
- The industry evolved through three phases: UTI monopoly, public sector entry, and private sector liberalization post-1993, each expanding choice and access.
- SEBI’s regulatory framework — introduced in 1993 and strengthened in 1996, 2002, and 2016 — has been central to ensuring transparency, investor protection, and fair competition.
- Today, India’s mutual fund industry manages over ₹50 lakh crore in AUM with more than 18 crore folios, reflecting deepening retail participation.
- ELSS funds exemplify how regulatory innovation (like SEBI oversight) and product design (three-year lock-in, equity exposure) combine to serve dual goals of tax saving and long-term wealth creation.
Chapter 2
How Mutual Funds Work: Mechanics and Selection
How NAV Works and How Returns Are Generated
The Net Asset Value (NAV) of a mutual fund is the cornerstone of how investors measure value and track performance. It represents the per-unit price at which you buy into or sell out of a fund, and it changes daily based on the market value of the fund’s underlying holdings. Understanding NAV is essential not only for knowing what you pay or receive when transacting, but also for accurately calculating returns over time.
How NAV Is Calculated
At the end of each trading day, the fund house computes the total market value of all securities held by the scheme — such as stocks, bonds, and cash equivalents — and subtracts any liabilities, including fund expenses payable and other obligations. The resulting net asset value is then divided by the number of outstanding units to arrive at the NAV per unit.
The formula is:
NAV = (Total Value of Assets – Total Liabilities) / Number of Outstanding Units
For example, suppose a mutual fund scheme holds:
- Equity shares valued at ₹8.2 crore
- Debt instruments worth ₹1.5 crore
- Cash and cash equivalents of ₹30 lakh
Total assets = ₹10.0 crore
Liabilities include:
- Accrued management fees: ₹8 lakh
- Other payables: ₹2 lakh
Total liabilities = ₹10 lakh
Net assets = ₹10.0 crore – ₹0.1 crore = ₹9.9 crore
If the scheme has 99 lakh outstanding units, the NAV per unit is: ₹9,90,00,000 / 9,90,000 = ₹100
This NAV is published daily by the fund house and used for all purchases and redemptions that day. Investors buying or selling units do so at this price, adjusted for any applicable load (though most funds today are no-load).
How Returns Are Generated in a Mutual Fund
Returns in a mutual fund come from three primary sources, all of which are reflected in changes to the NAV over time:
- Capital Appreciation: When the market value of the fund’s holdings (e.g., stocks or bonds) increases, the NAV rises. For instance, if a fund’s equity portfolio gains value due to rising share prices, this directly boosts NAV.
- Dividends: When companies in the fund’s portfolio declare dividends, the fund receives cash. This cash is either distributed to investors (in dividend payout options) or reinvested to buy more units (in dividend reinvestment or growth options). In the latter case, the NAV increases because the fund’s assets grow without a corresponding increase in liabilities.
- Interest Income: For debt holdings, interest earned on bonds or money market instruments adds to the fund’s income, increasing net assets and thus NAV.
Importantly, these returns are not paid out separately in most cases; instead, they are retained within the fund and reflected in the NAV. This means your profit or loss is determined by the difference between the NAV at which you bought and the NAV at which you sold — assuming no dividends were paid out in cash.
To illustrate, consider an investor who purchases 1,000 units of a fund at an NAV of ₹50, investing ₹50,000. One year later, the NAV is ₹58. If the fund has not paid out any dividends, the investor’s holding is now worth 1,000 × ₹58 = ₹58,000, representing a 16% return.
However, if the fund declared a dividend of ₹2 per unit during the year and paid it out in cash, the investor would have received ₹2,000 (1,000 × ₹2). On the dividend payment date, the NAV would drop by approximately ₹2 (to reflect the outflow of cash), say from ₹60 to ₹58. If the NAV at year-end is ₹58, the total value is:
- Current holding: 1,000 × ₹58 = ₹58,000
- Cash received: ₹2,000
- Total value: ₹60,000
- Return: (₹60,000 – ₹50,000) / ₹50,000 = 20%
This shows that dividends, when paid out, contribute to total return but reduce NAV. In growth options, dividends are reinvested, so the NAV reflects the full compounding effect.
Worked Example: NAV and Return Calculation Over One Year
Let’s walk through a detailed example to see how NAV evolves and how returns are computed.
Initial Investment (Day 1):
- Investor buys 500 units of an equity mutual fund at an NAV of ₹120
- Total investment = 500 × ₹120 = ₹60,000
During the Year:
- The fund’s portfolio appreciates, increasing the value of holdings
- The fund receives ₹8 per unit in dividends from equity holdings
- Instead of paying out the dividend, the fund reinvests it by purchasing additional units at the prevailing NAV
Dividend Reinvestment Process: On the dividend record date, the fund announces a dividend of ₹8 per unit.
- Total dividend payout = 500 units × ₹8 = ₹4,000
- This amount is used to buy new units at the current NAV. Assume the NAV on that date is ₹128 (before adjustment)
- Number of new units purchased = ₹4,000 / ₹128 = 31.25 units
- After reinvestment, total units held = 500 + 31.25 = 531.25 units
- The NAV drops by ₹8 on the ex-dividend date to reflect the payout, so post-adjustment NAV = ₹128 – ₹8 = ₹120
Year-End:
- By the end of the year, the fund’s NAV has grown to ₹140 due to continued capital appreciation
- The investor now holds 531.25 units
- Current value = 531.25 × ₹140 = ₹74,375
- Initial investment = ₹60,000
- Absolute gain = ₹74,375 – ₹60,000 = ₹14,375
- Percentage return = (₹14,375 / ₹60,000) × 100 = 23.96%
This return includes both capital appreciation and the compounding effect of reinvested dividends. Had the fund paid out the dividend in cash, the investor would have received ₹4,000, and the final holding would be 500 units × ₹140 = ₹70,000, for a total value of ₹74,000 and a return of 23.33% — slightly lower due to the lack of reinvestment at the prevailing NAV.
Growth vs. Dividend Options: How Returns Are Treated
Mutual funds typically offer two main options for handling returns: growth and dividend (which includes payout and reinvestment variants). The choice affects how returns are reflected in your investment and impacts taxation and cash flow.
In the growth option, all earnings — capital gains, dividends, and interest — are retained within the fund and reinvested. There are no periodic payouts. The investor’s return is realized solely through an increase in the number of units’ value (NAV growth). This option is ideal for investors focused on long-term wealth creation who do not need regular income.
In the dividend payout option, the fund distributes a portion of its surplus (from dividends or profits) to investors at regular intervals. When a dividend is declared, the NAV falls by approximately the amount of the payout (since cash leaves the fund). Investors receive the dividend in their bank account but see a corresponding drop in the value of their holding. This option suits those seeking periodic income, such as retirees.
The dividend reinvestment option automatically uses declared dividends to buy more units of the same fund at the prevailing NAV. While functionally similar to the growth option in terms of compounding, it differs in how transactions are recorded: each reinvestment creates a new lot of units with its own purchase date and NAV, which can complicate tax tracking (especially for capital gains calculations). As a result, many investors and advisors now prefer the growth option for its simplicity and cleaner accounting.
For example, consider two investors who each invest ₹1 lakh in the same fund at an NAV of ₹100:
- Investor A chooses the growth option
- Investor B chooses the dividend payout option
After one year:
- The fund’s NAV grows to ₹130 due to capital appreciation
- It also declares a dividend of ₹10 per unit
Investor A (growth):
- Still holds 1,000 units (no change in unit count)
- Value = 1,000 × ₹130 = ₹1,30,000
- Return = 30%
Investor B (dividend payout):
- Receives dividend: 1,000 units × ₹10 = ₹10,000 in cash
- On dividend date, NAV drops by ₹10 (from ₹140 to ₹130, assuming pre-dividend NAV was ₹140)
- Holding value = 1,000 × ₹130 = ₹1,30,000
- Total value = ₹1,30,000 + ₹10,000 = ₹1,40,000
- Return = 40%
At first glance, Investor B appears to have earned more. However, this comparison assumes the dividend was paid out of current profits without affecting future growth. In reality, the ₹10,000 paid out is no longer invested in the fund, so its potential to compound is lost. Over multiple years, the growth option often outperforms due to uninterrupted compounding, especially in equity funds where reinvestment drives long-term wealth.
Moreover, from a tax perspective, dividends paid out of mutual funds are now taxable in the hands of the investor at their income tax slab rate (since the abolition of dividend distribution tax in 2020), while growth option returns are taxed only upon redemption, allowing for tax deferral and potentially lower effective taxation through long-term capital gains benefits.
Why NAV Matters for Investors
NAV is more than just a pricing mechanism — it is a tool for tracking performance, comparing funds, and making informed decisions. By monitoring NAV trends, you can assess whether a fund is delivering on its objective. A consistently rising NAV over time, adjusted for dividends, indicates effective capital appreciation.
However, NAV alone should not be used to judge a fund’s quality. A lower NAV does not mean a fund is “cheaper” or better — it may simply reflect a higher number of units outstanding due to past dividends or a different face value. Similarly, a higher NAV does not imply superior performance. What matters is the percentage change in NAV over time, adjusted for any payouts.
For instance, Fund X with an NAV of ₹20 that rises to ₹24 gives a 20% return. Fund Y with an NAV of ₹200 that rises to ₹240 also gives a 20% return. Despite the tenfold difference in NAV, the returns are identical.
To evaluate performance accurately, investors should look at:
- Point-to-point returns (e.g., annualized returns over 1, 3, or 5 years)
- Rolling returns to assess consistency
- Returns adjusted for dividends (especially in dividend options)
- Benchmark comparison and risk-adjusted metrics (covered in later sections)
Ultimately, NAV provides the foundation for all return calculations. By understanding how it is computed and how it responds to market movements, income, and investor actions, you gain clarity on how your money is working — and how to measure its growth accurately over time.
Direct vs. Regular Plans: Understanding the Cost Difference
Mutual funds in India are offered in two variants: direct plan and regular plan. Both invest in the same underlying portfolio managed by the same fund manager, but they differ in how they are sold and the associated costs.
In a regular plan, you invest through an intermediary such as a distributor, broker, or financial advisor. The fund house pays a commission to this intermediary for sourcing and servicing the investment. This cost is recovered from the fund’s assets and reflected in a higher expense ratio — the annual fee charged to manage the fund, expressed as a percentage of average assets under management.
In a direct plan, you invest directly with the fund house, bypassing intermediaries. No distribution commission is paid, so the expense ratio is lower. The difference in expense ratios between direct and regular plans typically ranges from 0.5% to 1.5% per annum, depending on the fund category.
This cost difference compounds over time. For example, consider an investment of ₹5 lakhs in an equity fund with an expected annual return of 12% before expenses.
- In a regular plan with an expense ratio of 2.0%, the net return is approximately 10.0%.
- In a direct plan with an expense ratio of 1.0%, the net return is approximately 11.0%.
After 10 years:
- Regular plan: ₹5,00,000 × (1.10)^10 ≈ ₹12,96,871
- Direct plan: ₹5,00,000 × (1.11)^10 ≈ ₹14,19,513
The direct plan yields about ₹1.22 lakhs more — not because of better fund performance, but due to lower costs. Over longer horizons or larger sums, this gap widens significantly.
To identify the plan type, check the fund name on the factsheet or transaction statement. Direct plans usually include the word “Direct” in the name (e.g., “ABC Equity Fund Direct Plan-Growth”), while regular plans may simply say “ABC Equity Fund-Growth” or imply regular by omission.
If you are comfortable selecting and monitoring funds on your own — or using a fee-only advisor — the direct plan is generally preferable for long-term wealth creation. Regular plans may suit those who value advisory support and are willing to pay for it, provided the cost is transparent and justified.
Growth, Dividend Payout, and Dividend Reinvestment Options: How Returns Are Handled
As introduced in the previous section, mutual funds offer different options to handle returns: growth, dividend payout, and dividend reinvestment. These options determine how earnings — such as dividends, interest, and realized capital gains — are treated within the fund.
In the growth option, all earnings are retained and reinvested in the fund. There are no cash payouts. Your return comes entirely from the appreciation in NAV. This option supports uninterrupted compounding and is ideal for investors focused on long-term goals like retirement or wealth accumulation, especially when regular income is not needed.
In the dividend payout option, the fund distributes a portion of its surplus to investors at intervals (e.g., monthly, quarterly, or annually). When a dividend is declared, the NAV drops by approximately the dividend amount, as cash leaves the fund. You receive the payout in your bank account. This option suits investors seeking periodic income, such as retirees or those supplementing their cash flow.
However, as noted earlier, dividends from mutual funds are now taxable in your hands at your income tax slab rate (post-2020). This reduces the tax efficiency of the dividend payout option, particularly for high-income earners.
The dividend reinvestment option automatically uses declared dividends to purchase additional units of the same fund at the prevailing NAV. While this mirrors the compounding effect of the growth option, it creates multiple lots of units — each with its own purchase date and NAV. This complicates tax calculations, especially when redeeming partially, as each lot may attract different capital gains treatment based on holding period.
For instance, if you reinvest dividends monthly over three years, you could have 36 separate lots to track upon redemption. Determining long-term vs. short-term capital gains requires identifying which lots were held for over one year — a tedious process without proper software or professional help.
Because of this administrative burden and the availability of cleaner alternatives, many financial planners now recommend the growth option for most investors, even those seeking income. If you need regular cash flow, consider a Systematic Withdrawal Plan (SWP) from a growth option fund — a more tax-efficient and flexible alternative, as discussed later.
Systematic Investment Plan (SIP): Building Discipline Through Rupee Cost Averaging
A Systematic Investment Plan (SIP) allows you to invest a fixed amount at regular intervals (e.g., monthly or quarterly) into a mutual fund scheme. Instead of trying to time the market, you buy units regardless of whether the NAV is high or low, which leads to rupee cost averaging.
When the NAV is high, your fixed investment buys fewer units. When the NAV is low, the same amount buys more units. Over time, this averages out the cost per unit, reducing the impact of market volatility.
For example, suppose you start a monthly SIP of ₹10,000 in an equity fund over six months, with the following NAVs:
| Month | NAV (₹) | Units Purchased (₹10,000 ÷ NAV) |
|---|---|---|
| 1 | 100 | 100.00 |
| 2 | 90 | 111.11 |
| 3 | 110 | 90.91 |
| 4 | 95 | 105.26 |
| 5 | 105 | 95.24 |
| 6 | 100 | 100.00 |
| Total | — | 602.52 |
Total invested: ₹60,000 Average NAV if invested lump sum at start: ₹100 Actual average cost per unit: ₹60,000 ÷ 602.52 ≈ ₹99.58 Final value (assuming NAV rises to ₹110 in month 7): 602.52 × ₹110 ≈ ₹66,277 Return: (₹66,277 – ₹60,000) / ₹60,000 ≈ 10.46%
Had you invested ₹60,000 as a lump sum in month 1 at NAV ₹100, you’d have 600 units. At NAV ₹110, value would be ₹66,000 — a return of 10%. The SIP delivered a slightly better outcome due to buying more units during lower NAV months.
Beyond rupee cost averaging, SIPs promote financial discipline. By automating investments, you avoid emotional decisions driven by market highs or lows. You also benefit from compounding, as returns are reinvested and generate further returns over time.
SIPs are accessible — you can start with as little as ₹500 per month — and flexible. You can pause, increase, or stop the SIP based on your cash flow. They work particularly well for salaried individuals aiming to build wealth for long-term goals like a child’s education, home purchase, or retirement.
Systematic Transfer Plan (STP) and Systematic Withdrawal Plan (SWP): Tools for Allocation and Income
While SIPs help you invest regularly, Systematic Transfer Plan (STP) and Systematic Withdrawal Plan (SWP) serve specific tactical purposes in managing your portfolio.
An STP allows you to transfer a fixed amount from one mutual fund scheme to another — usually from a debt fund to an equity fund, or vice versa — at regular intervals. It is commonly used to deploy a lump sum into equity markets gradually, reducing timing risk.
For example, if you have ₹12 lakhs to invest in equity but are concerned about market volatility, you could park the amount in a liquid or ultra-short-term debt fund and set up an STP of ₹1 lakh per month into an equity fund over 12 months. This way, you benefit from potential market dips (buying more units when NAV is low) while earning modest returns on the parked amount.
Conversely, STP can also be used to shift gains from equity to debt as you approach a goal — say, moving money out of an equity fund 12–18 months before a child’s college admission to protect the corpus from market downturns.
An SWP, on the other hand, allows you to withdraw a fixed amount from your mutual fund investment at regular intervals. The fund sells enough units to meet the withdrawal amount, and the remaining balance continues to stay invested.
SWP is ideal for generating regular income in retirement or for meeting periodic expenses. Unlike dividend payouts — which are irregular, taxable at slab rates, and reduce the invested capital — SWP offers more control over timing and amount. Additionally, withdrawals can be structured to favor long-term capital gains taxation if held over one year (in equity funds), making them more tax-efficient.
For instance, suppose you have ₹50 lakhs invested in an equity fund via the growth option, with a current NAV of ₹250 (20,000 units). You set up an SWP of ₹25,000 per month.
In the first month:
- Amount to withdraw: ₹25,000
- Units to redeem: ₹25,000 ÷ ₹250 = 100 units
- Remaining units: 19,900
- Assuming NAV grows to ₹260 next month, value before withdrawal: 19,900 × ₹260 = ₹5,17,400
- After withdrawal of ₹25,000, remaining value: ₹4,92,400 (1,893.85 units at ₹260)
Over time, if the fund’s returns exceed the withdrawal rate, your corpus may last longer or even grow despite withdrawals. SWP also avoids the tax inefficiency of dividend payouts, as only the capital gains portion of each withdrawal is taxed (and potentially at lower LTCG rates).
Together, SIP, STP, and SWP form a toolkit for aligning mutual fund investing with your life stages: SIP for accumulation, STP for tactical allocation shifts, and SWP for distribution. When combined with the right plan (direct) and option (growth), they enable a disciplined, cost-effective, and goal-oriented investment approach.
Evaluating Mutual Fund Performance: Beyond Past Returns
When assessing a mutual fund, it is tempting to look first at its recent returns. A fund that has delivered 20% annualized returns over the past year may seem like a clear winner. However, past performance alone is an unreliable predictor of future results. Market conditions change, fund managers shift strategies, and asset classes rotate in and out of favor. Relying solely on historical returns can lead to chasing last year’s top performer, only to find it underperforming in the next cycle.
Consider two equity funds over a five-year period. Fund A returned 18% CAGR, while Fund B returned 12%. At first glance, Fund A appears superior. But when you examine the journey, Fund A experienced a 40% drawdown during a market correction, whereas Fund B’s maximum drawdown was only 15%. Fund A’s higher return came with significantly more volatility, which may not align with your risk tolerance. If you had invested in Fund A and panicked during the downturn, you might have exited at a loss, undermining the very goal of wealth creation.
This is why a robust evaluation framework must go beyond returns to include risk-adjusted performance, consistency, and qualitative strengths. The goal is not to find the fund with the highest return, but the one that best balances return potential with risk control, aligns with your investment horizon, and is managed by a credible team with a repeatable process.
Quantitative Metrics: Measuring Return and Risk
Quantitative metrics provide objective, comparable data to assess how a fund has performed relative to its risk and benchmark. These numbers are typically found in the fund’s factsheet or fact sheet and should be evaluated over meaningful time frames—three, five, and ten years—to capture different market cycles.
Compound Annual Growth Rate (CAGR) measures the mean annual growth rate of an investment over a specified period longer than one year. It smooths out volatility to show what steady annual return would have produced the same ending value. For example, if a fund’s NAV grew from ₹100 to ₹180 over three years, the CAGR is approximately 21.6%—not a simple average of yearly returns, but the constant rate that compounds to the final amount.
However, CAGR alone does not reveal how much risk was taken to achieve that return. Two funds with identical CAGRs may have very different risk profiles. This is where volatility and risk-adjusted ratios come in.
Standard deviation quantifies the dispersion of a fund’s returns around its average. A higher standard deviation indicates greater variability in monthly or yearly returns, implying higher volatility. For instance, a large-cap equity fund might have a three-year standard deviation of 18%, while a sectoral fund could exceed 30%. If you are investing for a goal five years away, a fund with excessively high standard deviation may expose you to unacceptable short-term losses.
To assess whether a fund’s returns are commensurate with the risk taken, investors use the Sharpe ratio. It measures excess return (return above the risk-free rate, such as a government bond yield) per unit of volatility (standard deviation). A Sharpe ratio above 1.0 is generally considered good; above 2.0 is excellent. For example, if Fund X returns 14% with a standard deviation of 10% and the risk-free rate is 6%, its Sharpe ratio is (14% – 6%) / 10% = 0.8. Fund Y returns 12% with a standard deviation of 6% gives a Sharpe ratio of (12% – 6%) / 6% = 1.0. Despite Fund X’s higher return, Fund Y delivers better risk-adjusted performance.
Alpha measures a fund’s outperformance relative to its benchmark, after adjusting for risk (beta). A positive alpha indicates the fund manager has added value through security selection or timing. For example, if a fund’s benchmark returned 10% and the fund returned 13%, but the fund’s beta is 1.1, the expected return based on market movement would be higher than 10%. Alpha isolates the portion of return attributable to managerial skill.
Beta measures a fund’s sensitivity to market movements. A beta of 1.0 means the fund moves in line with the market. A beta of 1.2 suggests the fund is 20% more volatile than the benchmark; a beta of 0.8 indicates 20% less volatility. For conservative investors, a lower-beta equity fund may offer market participation with reduced swing. For aggressive investors seeking higher returns, a higher-beta fund may be appropriate—provided they can tolerate the increased fluctuations.
These metrics are most useful when compared within the same fund category. Comparing the Sharpe ratio of a liquid fund to that of a small-cap fund is misleading due to inherent differences in risk profiles. Always benchmark against peers.
Qualitative Factors: The Human and Structural Elements
Numbers tell part of the story, but qualitative factors reveal the sustainability of performance. A fund with strong metrics but a high-turnover management team or opaque processes may not maintain its edge.
Fund house quality is foundational. Look for asset management companies (AMCs) with a long track record, sound governance, and consistent adherence to investment philosophy. AMCs that prioritize research, risk management, and client interests over asset gathering tend to produce more reliable outcomes. Check if the fund house has avoided major regulatory penalties and maintains transparency in disclosures.
Fund manager tenure and experience matter significantly. A manager who has steered a fund through multiple market cycles—bull, bear, and sideways—is more likely to have navigated volatility effectively than a newcomer. Review the manager’s track record not just in this fund, but in previous roles. Consistency in investment approach, rather than frequent style shifts, signals discipline.
Portfolio diversification affects risk concentration. Even within an equity fund, holding more than 40–50% of assets in the top five stocks increases vulnerability to company- or sector-specific shocks. For example, a fund heavily weighted in financial services may suffer disproportionately if interest rates rise or loan defaults increase. Examine the factsheet’s portfolio holdings and sector allocation to gauge diversification. A well-diversified fund spreads risk across 40–60 stocks and multiple sectors.
Expense ratio directly impacts net returns. While seemingly small, a 1% difference in annual expenses compounds significantly over time. A direct plan typically has a lower expense ratio than a regular plan due to the absence of distributor commissions. Over 20 years, a fund with a 1.5% expense ratio will leave you with substantially less than an otherwise identical fund charging 0.5%, assuming the same gross return. Always opt for the direct plan unless you require advisory services that justify the higher cost.
Step-by-Step Evaluation Checklist
Use this checklist to systematically evaluate a mutual fund using publicly available factsheet data. Apply it to funds within the same category (e.g., large-cap, flexi-cap, ELSS) for meaningful comparison.
| Evaluation Criteria | What to Look For | Source |
|---|---|---|
| Return Consistency | CAGR over 3, 5, and 10 years; compare to category average and benchmark | Factsheet performance table |
| Risk Metrics | Standard deviation, Sharpe ratio; favor higher Sharpe for better risk-adjusted return | Factsheet risk section |
| Risk-Adjusted Performance | Positive and consistent alpha over 3+ years; indicates skill, not just market beta | Factsheet or fund overview |
| Market Sensitivity | Beta close to 1.0 for market-like movement; higher or lower based on your risk tolerance | Factsheet |
| Expense Ratio | Lower is better; prefer direct plan; compare to category average | Factsheet fee section |
| Fund Manager Tenure | At least 3–5 years managing the fund; review past performance | Factsheet fund details |
| Fund House Reputation | Longevity, regulatory compliance, investment philosophy clarity | AMC website, news, disclosures |
| Portfolio Concentration | Top 5 holdings < 40–50%; sector allocation not overly skewed | Factsheet portfolio holdings |
| Turnover Ratio | Lower turnover suggests buy-and-hold approach; very high turnover may increase costs | Factsheet or scheme information document |
| AUM and Liquidity | Very small AUM (< ₹500 cr) may face liquidity issues; very large AUM (> ₹50,000 cr) may limit agility | Factsheet fund details |
Begin by narrowing your universe to funds matching your goal—say, ELSS for tax saving and long-term growth. Then, apply the checklist to eliminate those with high expense ratios, manager turnover under two years, or concentrated portfolios. From the remaining candidates, compare Sharpe ratios and alpha to identify funds that have delivered returns efficiently. Finally, review the fund’s investment strategy to ensure it aligns with your beliefs—for instance, whether it follows a value, growth, or blended approach.
No single metric tells the whole story. A fund with a modest Sharpe ratio but a veteran manager navigating a difficult market may still be preferable to a high-Sharpe fund driven by temporary momentum. By combining quantitative rigor with qualitative judgment, you move beyond past returns to build a portfolio grounded in reason, not reaction. This disciplined approach increases the odds of achieving your financial objectives across market cycles.
Reading a Mutual Fund Factsheet: A Practical Guide
A mutual fund factsheet is a standardized document published monthly by the asset management company (AMC). It distills essential information about the fund into a scannable format, enabling investors to compare options and monitor existing holdings. Think of it as the fund’s nutritional label—it doesn’t tell you everything, but it highlights what matters most for making informed decisions. Learning to read it effectively turns passive browsing into active evaluation.
Navigating the Core Sections
Every factsheet follows a similar structure, though wording and emphasis may vary slightly between AMCs. Start at the top with the fund’s basic identity: name, scheme type (e.g., open-ended equity scheme), and the date the factsheet was issued. Below this, you’ll find clearly labeled sections that answer key questions.
Fund Objective and Strategy This section states the fund’s primary goal and how the manager intends to achieve it. For an ELSS fund, it might read: “To generate long-term capital appreciation by investing predominantly in equity and equity-related instruments while providing tax benefits under Section 80C of the Income Tax Act.” Notice the dual focus—wealth creation and tax efficiency. The strategy will often mention the market-cap orientation (e.g., “focus on large-cap companies”) or investment style (e.g., “bottom-up, research-driven approach”). If the objective feels vague or overly broad—such as “to seek growth through opportunistic investments”—treat it as a yellow flag. Clarity here correlates with disciplined execution.
Asset Allocation This shows how the fund’s money is split across asset classes, typically presented as a pie chart or bar graph. For an equity fund like most ELSS schemes, you’ll see the bulk allocated to stocks (e.g., 85–95%), with the remainder in debt, cash, or arbitrage. The factsheet will also list the actual and permitted ranges. For example:
- Equity: 88% (actual), 80–100% (permitted)
- Debt: 8% (actual), 0–20% (permitted)
- Cash & Equivalents: 4% (actual), 0–10% (permitted)
Staying within the permitted range indicates adherence to the fund’s mandate. Frequent breaches suggest style drift—where the manager is taking unintended risks. Compare this to the fund’s category average. If an ELSS fund consistently holds only 70% in equity while peers average 88%, it may be too conservative for long-term growth goals.
Top Holdings and Sector Allocation These sections reveal where the fund’s money is actually invested. The top holdings list usually shows the five to ten stocks with the largest weightings, expressed as a percentage of net assets. For instance:
- HDFC Bank Ltd. – 9.2%
- Infosys Ltd. – 8.1%
- ICICI Bank Ltd. – 7.5%
- Reliance Industries Ltd. – 6.8%
- Tata Consultancy Services Ltd. – 6.2%
If the top five holdings exceed 40–50% of the portfolio, concentration risk rises. In the example above, the top five total 37.8%, which is acceptable. But if they summed to 55%, a single sector downturn (e.g., banking) could disproportionately impact returns.
Sector allocation breaks down equity exposure by industry. A well-diversified ELSS fund might show:
- Financial Services: 28%
- Information Technology: 18%
- Oil & Gas: 12%
- Consumer Goods: 10%
- Healthcare: 9%
- Others: 23%
Watch for overexposure. If financial services exceed 35% or IT crosses 25%, the fund becomes a leveraged bet on those sectors. This isn’t inherently bad—but it should align with your risk tolerance and conviction. If you’re already heavily invested in bank stocks directly, doubling down via a fund may unintentionally concentrate your risk.
Interpreting Performance and Risk Metrics
Performance data is historical but critical for assessing consistency. The factsheet typically shows returns for various periods (1 month, 6 months, 1 year, 3 years, 5 years, since inception) alongside the fund’s benchmark and category average.
Benchmark Comparison Every fund has a designated benchmark index (e.g., Nifty 500 TRI for flexi-cap, Nifty 500 TRI for many ELSS funds). The factsheet will display how the fund’s returns stack up against this index over time. For example:
| Period | Fund Return | Nifty 500 TRI | Category Avg (ELSS) |
|---|---|---|---|
| 1 Year | 12.4% | 10.1% | 11.0% |
| 3 Years | 14.2% | 13.5% | 13.0% |
| 5 Years | 15.8% | 14.9% | 14.5% |
Here, the fund outperforms both its benchmark and the category average across all periods—a strong sign of skill. If the fund only beats the benchmark in bull markets but lags in downturns, examine whether the outperformance comes from taking excessive risk.
Risk Metrics Look for standard deviation (volatility), Sharpe ratio (risk-adjusted return), and beta (market sensitivity). These appear in a dedicated “Risk Measures” table. Using the same ELSS fund example:
| Metric | Fund Value | Category Avg (ELSS) | Interpretation |
|---|---|---|---|
| Standard Dev (3Y) | 18.5% | 19.0% | Slightly lower volatility than peers |
| Sharpe Ratio (3Y) | 0.68 | 0.60 | Better risk-adjusted return than average |
| Beta (3Y) | 0.92 | 0.95 | Moves slightly less than the market |
A Sharpe ratio above 0.5 is generally respectable for equity funds over three years; above 0.75 is strong. Beta below 1.0 suggests the fund is less volatile than the market—useful if you prefer smoother rides. If beta creeps above 1.20, the fund amplifies market swings, which may not suit conservative goals.
Spotting Red Flags
Not all factsheets tell a clean story. Learn to spot inconsistencies that hint at deeper issues.
High Portfolio Turnover Turnover ratio measures how frequently the fund buys and sells securities. It’s expressed as a percentage of average assets. A ratio of 80% means the fund replaced roughly four-fifths of its holdings in a year. High turnover increases transaction costs and can erode returns, especially in taxable accounts (though less relevant for ELSS due to the lock-in). If an ELSS fund shows a turnover ratio of 120% while the category average is 80%, question whether the manager is chasing short-term trends rather than adhering to a stated long-term strategy.
Inconsistent Risk-Adjusted Returns Sometimes a fund shows high raw returns but poor risk-adjusted metrics. For instance, a fund might deliver 16% CAGR over five years with a Sharpe ratio of only 0.40—indicating the return came at the cost of excessive volatility. Contrast this with another fund delivering 14% CAGR and a Sharpe ratio of 0.70. The latter achieved more return per unit of risk, suggesting better skill. Always pair return figures with Sharpe or Sortino ratios to assess efficiency.
Style Drift or Strategy Shifts Check the factsheet’s “Fund Details” section for changes in fundamental attributes. Has the benchmark changed recently? Has the fund’s market-cap focus shifted from large-cap to flexi-cap without clear justification? Such shifts, especially if unexplained in the fund manager’s commentary, may signal reactive decision-making rather than conviction. Similarly, if the fund manager tenure drops below two years, reassess whether the historical performance still reflects the current team’s capability.
Try This
Apply what you’ve learned this week:
- Download the latest factsheet for any ELSS fund you’re considering (e.g., from the AMC’s website or a portal like Value Research).
- Identify the top five holdings and calculate their combined weight. Is it below 50%?
- Compare the fund’s 3-year Sharpe ratio to the category average. Is it higher, lower, or about the same?
Key Takeaways
- A mutual fund factsheet provides standardized, comparable data on objective, allocation, holdings, performance, and risk.
- Use asset and sector allocation charts to assess diversification; avoid funds where top holdings exceed 50% or a single sector dominates beyond 35%.
- Always evaluate returns alongside risk metrics like Sharpe ratio and beta—high returns with high volatility may not suit your goals.
- Watch for red flags: high turnover ratio, unexplained benchmark or strategy changes, and short manager tenure.
- Combine factsheet analysis with qualitative judgments about fund house quality and manager consistency for a complete evaluation.
Chapter 3
ELSS and Tax-Saving Investments: Strategy and Execution
What Is ELSS? Features, Lock-in, and Tax Benefits
Imagine investing ₹1.5 lakh every year and seeing your taxable income drop by the same amount, while your money grows in the market with the potential to outpace inflation. This is the promise of Equity Linked Savings Schemes, or ELSS — a mutual fund category designed specifically for tax-saving and long-term wealth creation. As you move from understanding how mutual funds work to applying that knowledge to tax planning, ELSS stands out as a unique tool that combines the growth potential of equities with the benefit of a Section 80C deduction.
What Is ELSS?
ELSS is an open-ended equity mutual fund that primarily invests in stocks and equity-related instruments. Like other mutual funds, it pools money from many investors and is managed by a professional fund manager who selects stocks based on the fund’s objective. What sets ELSS apart is its dual purpose: it helps you save tax under Section 80C of the Income Tax Act while aiming for capital appreciation over the long term.
Because it invests predominantly in equities — typically 80% or more of its assets — ELSS carries market risk, meaning its net asset value (NAV) can fluctuate with stock prices. However, this equity exposure also gives it the potential to deliver higher returns compared to traditional fixed-income tax-saving instruments over extended periods.
Lock-in Period: Three Years, No Exceptions
Every ELSS investment comes with a mandatory lock-in period of three years. This means that once you invest, you cannot redeem or withdraw your units before this period ends, regardless of market conditions or personal financial needs. The lock-in applies to each installment separately if you invest via a systematic investment plan (SIP). For example, if you start a monthly SIP of ₹10,000 in January 2024, the January installment locks in until January 2027, the February installment until February 2027, and so on.
This three-year lock-in is the shortest among all Section 80C options. Instruments like the Public Provident Fund (PPF) and National Savings Certificate (NSC) have lock-ins of 15 and five years, respectively, while tax-saving fixed deposits (FDs) lock in for five years. The shorter lock-in in ELSS offers greater liquidity relief compared to other tax-saving avenues, allowing you to access your funds sooner after the initial commitment.
Tax Benefits: Deduction and Treatment of Gains
ELSS provides tax benefits at two stages: investment and redemption.
First, you can claim a deduction of up to ₹1.5 lakh per financial year under Section 80C for your ELSS investments. This reduces your taxable income directly. For instance, if your annual taxable income is ₹10 lakh and you invest ₹1.5 lakh in ELSS, your taxable income drops to ₹8.5 lakh, potentially saving you ₹45,000 in taxes if you fall in the 30% tax bracket (excluding cess and surcharge).
Second, gains from ELSS are treated as long-term capital gains (LTCG) because equity holdings held for more than one year qualify as long-term. However, due to the three-year lock-in, you can only redeem after three years, making all eligible gains long-term by default. As per current tax rules, LTCG from equity funds exceeding ₹1 lakh in a financial year is taxed at 10% without the benefit of indexation. Gains up to ₹1 lakh per year remain tax-free.
For example, suppose you invest ₹1.5 lakh in ELSS and after three years, the value grows to ₹2.5 lakh, resulting in a gain of ₹1 lakh. Since this gain is exactly ₹1 lakh, it is entirely tax-free. If the gain were ₹1.3 lakh, only ₹30,000 (the amount exceeding ₹1 lakh) would be taxed at 10%, resulting in a tax liability of ₹3,000.
ELSS vs. Other 80C Options: A Comparison
To understand ELSS’s place in your tax-saving strategy, it helps to compare it with other popular Section 80C instruments. The table below outlines how ELSS stacks up against PPF, NSC, and tax-saving FDs on key parameters: returns, lock-in, risk, and tax treatment.
| Instrument | Returns (Indicative) | Lock-in | Risk Level | Tax on Gains |
|---|---|---|---|---|
| ELSS | 10–12% (market-linked) | 3 years | High (equity-linked) | 10% LTCG above ₹1 lakh |
| PPF | 7.1% (fixed, quarterly reset) | 15 years | Very low (government-backed) | Tax-free (EEE) |
| NSC | 7.7% (fixed) | 5 years | Low (government-backed) | Taxable as income |
| Tax-saving FD | 6–7% (fixed) | 5 years | Low (bank/CDB-backed) | Taxable as income |
Note: Returns for ELSS are indicative and based on historical performance; actual returns vary. PPF, NSC, and FD rates are as of the current financial year and subject to change.
This comparison highlights ELSS’s trade-off: it offers the highest return potential and the shortest lock-in but comes with higher risk due to equity exposure. In contrast, PPF, NSC, and tax-saving FDs provide fixed, guaranteed returns with lower risk but lock in your money for longer periods and, in the case of NSC and FDs, tax the gains as income.
For a salaried individual in the 20% or 30% tax bracket aiming to build wealth while saving tax, ELSS often presents a compelling option — especially when aligned with long-term goals like retirement or a child’s education, where a three-year horizon is just the beginning of a longer investment journey.
Consider the case of Aarav, a 30-year-old software engineer earning ₹12 lakh annually. He wants to save tax under Section 80C while also growing his wealth for a down payment on a house in seven years. Currently, he puts ₹1.5 lakh every year into a tax-saving fixed deposit, which gives him a guaranteed return of around 6.5% and reduces his taxable income. However, after accounting for tax on the interest earned — which is added to his income and taxed at his slab rate of 30% — his post-tax return drops to approximately 4.55%. Over seven years, this limits the growth of his savings.
Now, suppose Aarav redirects the same ₹1.5 lakh annual investment into an ELSS fund via a monthly SIP of ₹12,500. Assuming a conservative average annual return of 10% — well within the long-term range for diversified equity funds — his investment could grow to about ₹14.8 lakh after seven years. Even after paying 10% tax on LTCG exceeding ₹1 lakh per year upon redemption (starting from the fourth year, due to the three-year lock-in), his post-tax corpus would still likely exceed ₹13 lakh, significantly higher than what the tax-saving FD would yield.
This example illustrates why ELSS is not just a tax-saving tool but also a wealth-building instrument. The equity exposure allows your money to benefit from market growth over time, and the three-year lock-in, while restricting early access, encourages disciplined investing — a key factor in achieving long-term financial goals. It also means that each SIP installment becomes a fresh opportunity to invest, with returns compounding on both the principal and the accumulated gains.
It’s important to recognize that ELSS does not guarantee returns. In any given year, the NAV may fall due to market volatility, and short-term performance can be negative. However, historical data shows that over rolling three-year periods, diversified equity funds have delivered positive returns in a majority of cases, and the likelihood of loss decreases significantly with longer holding periods. For an investor with a horizon of five years or more — which aligns naturally with ELSS’s structure, given the lock-in encourages staying invested — the probability of achieving inflation-beating returns increases.
Moreover, because ELSS is open-ended, you retain the flexibility to continue holding your investment beyond the lock-in period. There is no obligation to redeem after three years. Many investors choose to keep their ELSS holdings invested for much longer, treating them as part of their core equity portfolio. This flexibility allows you to reassess based on your goals, market conditions, or changes in tax law — without being forced into a premature exit.
Finally, remember that the ₹1.5 lakh limit under Section 80C is cumulative across all eligible instruments, including ELSS, PPF, life insurance premiums, tuition fees, and principal repayment on home loans. If you’ve already used part of this limit through other commitments, your ELSS investment can fill the remaining gap. For instance, if you’ve paid ₹80,000 toward life insurance and ₹40,000 as your child’s tuition fee, you can still invest up to ₹30,000 in ELSS to maximize your Section 80C benefit.
By integrating ELSS into your tax planning, you’re not merely reducing your tax bill — you’re positioning your savings to grow in line with the economy’s long-term trajectory, all while adhering to a disciplined, goal-oriented investment approach.
Why ELSS Belongs in Your Tax-Saving Portfolio
ELSS stands out among Section 80C instruments not just for its tax benefits but for its ability to generate real, inflation-beating wealth over time. While traditional options like PPF or NSC offer safety, they often fall short in preserving purchasing power. ELSS, by contrast, leverages equity exposure to deliver growth that can outpace rising costs, making it a strategic choice for long-term financial goals. This section explains why ELSS deserves a central place in your tax-saving strategy, using data, comparisons, and practical insights to show how it combines tax efficiency with wealth creation.
Equity Advantage: Beating Inflation Over the Long Term
Inflation erodes the value of money, and fixed-return instruments often fail to keep pace. For example, if inflation averages 6% per year, a PPF return of 7.1% gives you a real return of just 1.1%. In contrast, ELSS funds, invested primarily in equities, have historically delivered returns of 10–12% over 10-year periods. Even after accounting for long-term capital gains (LTCG) tax, the post-tax return typically remains in the 8–9% range, translating to a real return of 2–3% — significantly higher than what PPF or tax-saving FDs offer after inflation.
This equity advantage matters because it allows your savings to grow in line with, or even exceed, the economy’s growth trajectory. Consider that the Nifty 50 has delivered a compound annual growth rate (CAGR) of around 12% over the past 15 years, despite short-term volatility. While past performance doesn’t guarantee future results, the probability of positive returns increases with holding period. Data from the Association of Mutual Funds in India (AMFI) shows that over rolling 10-year periods, diversified equity funds have delivered positive returns in over 95% of cases since 2000.
For a salaried investor, this means ELSS isn’t just about saving tax today — it’s about building a corpus that maintains or increases its purchasing power over time. If your goal is to fund a child’s higher education in 15 years or build a retirement nest egg, relying solely on low-return instruments could leave you falling short. ELSS bridges that gap by combining tax savings with growth potential.
Case Study: ELSS vs. PPF Over 10 Years
To illustrate the wealth creation difference, let’s compare investing ₹1.5 lakh annually in ELSS versus PPF over a 10-year horizon. Assume ELSS delivers an average annual return of 12% (pre-tax), while PPF offers a fixed 7.1% (as per current rates). We’ll also factor in LTCG tax on ELSS gains exceeding ₹1 lakh per year, applicable from the fourth year onward due to the three-year lock-in.
The table below shows the year-by-year growth of both investments, including tax impact on ELSS:
| Year | ELSS Investment (₹) | ELSS Corpus Before Tax (₹) | LTCG Tax (₹) | ELSS Corpus After Tax (₹) | PPF Corpus (₹) |
|---|---|---|---|---|---|
| 1 | 1,50,000 | 1,50,000 | 0 | 1,50,000 | 1,50,000 |
| 2 | 3,00,000 | 3,30,000 | 0 | 3,30,000 | 3,10,250 |
| 3 | 4,50,000 | 5,37,600 | 0 | 5,37,600 | 4,82,278 |
| 4 | 6,00,000 | 7,70,112 | 7,011 | 7,63,101 | 6,66,520 |
| 5 | 7,50,000 | 10,30,673 | 15,314 | 10,15,359 | 8,63,843 |
| 6 | 9,00,000 | 13,21,202 | 24,842 | 12,96,360 | 10,75,176 |
| 7 | 10,50,000 | 16,47,523 | 35,752 | 16,11,771 | 13,01,713 |
| 8 | 12,00,000 | 20,13,244 | 48,162 | 19,65,082 | 15,44,134 |
| 9 | 13,50,000 | 24,15,893 | 62,089 | 23,53,804 | 18,03,767 |
| 10 | 15,00,000 | 28,55,800 | 77,580 | 27,78,220 | 20,81,834 |
Note: LTCG tax is calculated at 10% on gains exceeding ₹1 lakh per financial year, applied only to the ELSS corpus growth from investments made more than three years prior. PPF returns are tax-free.
After 10 years, the ELSS corpus grows to approximately ₹27.78 lakh, while the PPF corpus reaches ₹20.82 lakh — a difference of nearly ₹7 lakh. This gap widens further with time due to compounding. Even if ELSS returns were more conservative at 10%, the post-tax corpus would still exceed ₹24 lakh, outperforming PPF by a significant margin.
This example shows that ELSS doesn’t just save tax — it actively grows your wealth. The higher return potential, combined with the discipline of a three-year lock-in per SIP installment, helps investors stay invested through market cycles, increasing the likelihood of achieving inflation-beating results.
Flexibility Post-Lock-In: Stay Invested or Redeem as Needed
A common misconception is that ELSS forces you to exit after three years. In reality, the lock-in applies only to each installment, and you are free to hold your investment beyond that period. This flexibility is a key strength. After the initial three years, you can choose to:
- Continue holding the ELSS fund as part of your long-term equity portfolio
- Redeem partially or fully to meet a financial goal
- Switch to another ELSS or equity fund based on performance or changing goals
For instance, if you start an SIP in ELSS at age 30 for a home down payment at age 40, each installment becomes available for redemption three years after it’s invested. By year seven, you begin to have access to early SIPs, allowing you to stagger redemptions as needed. Alternatively, if you don’t need the money, you can let the entire corpus grow — many investors treat ELSS as a core holding and stay invested for 10, 15, or even 20 years.
This post-lock-in flexibility distinguishes ELSS from rigid instruments like PPF (where partial withdrawals are restricted) or tax-saving FDs (which auto-renew or penalize early exit). It allows you to adapt your strategy as your life evolves — whether that means increasing equity exposure during a market dip, rebalancing toward debt as a goal nears, or simply staying the course.
Strategic Role: Combining Tax Saving with Goal-Based Investing
ELSS works best when it’s not viewed in isolation but as part of a broader financial plan. Its true value emerges when you align it with specific, long-term goals — such as retirement, a child’s education, or wealth creation — and use it to replace less efficient 80C instruments.
For example, if you’re currently putting ₹1.5 lakh into a tax-saving FD earning 6.5% (post-tax return ~4.55% for a 30% bracket holder), switching to ELSS could significantly enhance your corpus over time. Over 15 years, that same annual investment at a 10% post-tax return could grow to over ₹52 lakh, compared to roughly ₹29 lakh in the FD — nearly doubling your wealth.
This strategic shift makes sense when your goal horizon is five years or more. The three-year lock-in per SIP installment encourages discipline without locking away your entire corpus indefinitely. Over time, as early installments mature, you gain liquidity while the bulk of your investment continues to compound.
Moreover, because ELSS is open-ended and market-linked, it integrates smoothly with other equity investments. You can use it as the equity leg of your asset allocation, rebalancing periodically to maintain your desired risk profile. This approach ensures that your tax-saving effort doesn’t operate in a silo but actively contributes to your overall financial health.
By choosing ELSS, you’re not just checking a box for Section 80C — you’re putting your savings to work in a way that reflects both your present tax needs and your future aspirations. The key is to start early, stay invested through volatility, and let the power of equity compounding do the heavy lifting. Over time, this turns tax planning into wealth building — one SIP at a time.
Evaluating ELSS Funds: Key Criteria for Selection
Choosing the right ELSS fund requires more than glancing at star ratings or recent returns. While past performance offers a snapshot, it does not guarantee future results. A robust selection framework focuses on consistency, risk management, and alignment with your investment horizon. For ELSS, where the minimum lock-in is three years per SIP installment, you need a fund that can deliver steady growth across market cycles without taking excessive risks.
Consistency of Returns Across Market Cycles
Consistency matters because ELSS is a long-term wealth-building tool, not a short-term trading vehicle. You want a fund that preserves capital during downturns and participates meaningfully in upswings. Look for rolling returns over 3-, 5-, and 7-year periods to assess how the fund has performed across different market phases. A fund that ranks in the top quartile consistently over these periods demonstrates resilience and skill.
For example, consider two hypothetical ELSS funds over a 5-year period ending March 2024:
| Metric | Fund A | Fund B |
|---|---|---|
| 5-Year CAGR | 12.8% | 15.2% |
| 3-Year Rolling Return (min) | 8.1% | -2.3% |
| 3-Year Rolling Return (max) | 18.5% | 24.0% |
| Standard Deviation (3-Year) | 14.2% | 18.7% |
| Sharpe Ratio (3-Year) | 0.62 | 0.51 |
Fund B shows a higher point-to-point return but exhibits greater volatility and a negative minimum rolling return, indicating significant drawdowns during market stress. Fund A, while slightly lower in headline return, delivers more consistent outcomes with lower risk. The Sharpe ratio — which measures return per unit of risk — confirms Fund A offers better risk-adjusted performance. For an ELSS investor with a 3-year lock-in per SIP, avoiding large drawdowns is critical; you may not have the flexibility to wait out a prolonged recovery if you need liquidity soon after lock-in ends.
Assets Under Management and Expense Ratio
AUM size and expense ratio are practical filters that affect real-world returns. Extremely small AUM (e.g., below ₹500 crore) can lead to liquidity constraints and higher impact costs, especially in volatile markets. Conversely, very large AUM (e.g., above ₹20,000 crore) may limit a fund’s agility in mid- and small-cap stocks, though many ELSS funds manage this through diversified mandates.
Expense ratio directly reduces your take-home return. Since ELSS returns are market-linked, even a 1% difference in expenses compounds significantly over time. Assume two identical funds grossing 12% annually:
| Fund | Expense Ratio | Net Return (10 Years) on ₹1.5 Lakh SIP/Year |
|---|---|---|
| Fund X | 0.80% | ₹30.9 lakh |
| Fund Y | 2.20% | ₹25.1 lakh |
Over 10 years, Fund Y’s higher expense ratio costs you nearly ₹6 lakh in lost wealth — equivalent to four years of SIP contributions. While ELSS funds typically range between 0.50% and 2.50%, prioritize those below 1.50% unless superior performance justifies the cost. Always check the scheme information document (SID) for the total expense ratio (TER) and verify if it includes GST and other charges.
Fund Manager Tenure and Investment Process
The fund manager’s experience and stability are strong predictors of performance. ELSS funds rely heavily on stock selection and sector allocation, making the manager’s role pivotal. Look for managers with at least five years of tenure managing the fund or a similar mandate. Frequent changes disrupt continuity and may signal internal instability.
Equally important is the investment process. A disciplined, rule-based approach — such as focusing on quality growth, earnings momentum, or valuation discipline — tends to outperform ad hoc stock-picking. Review the fund factsheet for details on the investment strategy, portfolio turnover rate, and concentration levels.
For instance, Fund A is managed by a veteran with 12 years of experience, using a process that screens for companies with ROE > 15%, debt-to-equity < 0.5, and consistent earnings growth. The portfolio turnover is 45% annually, indicating low churn. Fund B, by contrast, has had three manager changes in four years, follows a thematic approach with high concentration in speculative sectors, and turns over 85% of its portfolio yearly — suggesting higher transaction costs and style drift risk.
Avoiding Common Pitfalls: Churn, Concentration, and Style Drift
High portfolio churn increases costs and can erode returns. A turnover ratio above 75% annually warrants scrutiny unless justified by a clear strategy (e.g., arbitrage). Similarly, concentrated bets — where top 5 holdings exceed 50% of assets — amplify risk. While some conviction is healthy, excessive concentration makes the fund vulnerable to single-stock or sector shocks.
Style drift occurs when a fund deviates from its stated mandate. An ELSS fund must maintain at least 80% equity exposure, but within that, it may shift from large-cap to mid/small-cap or from value to growth without notice. This can alter your risk profile unexpectedly. Check the factsheet’s market-cap breakdown and sector allocation over time. If a fund labeled “flexi-cap” suddenly holds 60% in small-caps when it previously held 30%, investigate whether the change aligns with the fund’s stated objective.
For example, Fund C started as a large-cap lean ELSS but gradually increased mid-cap exposure from 20% to 45% over two years without a change in mandate. While returns improved in a mid-cap rally, the fund’s volatility spiked, and it underperformed during the subsequent correction. Investors expecting large-cap stability were exposed to higher risk than anticipated.
Side-by-Side Comparison: Applying the Framework
To illustrate how these criteria work in practice, consider two real-world ELSS funds as of March 2024:
| Criteria | Fund Alpha | Fund Beta |
|---|---|---|
| 5-Year CAGR | 13.4% | 16.1% |
| 3-Year Min Rolling Return | 6.8% | -4.1% |
| Standard Deviation (3Y) | 13.9% | 19.3% |
| Sharpe Ratio (3Y) | 0.68 | 0.52 |
| Expense Ratio | 0.92% | 2.15% |
| Fund Manager Tenure | 8 years | 2 years (current) |
| Top 5 Holdings | 38% of AUM | 55% of AUM |
| Portfolio Turnover | 42% | 78% |
| AUM | ₹8,200 crore | ₹1,400 crore |
| Market-Cap Allocation | Large: 65%, Mid: 25%, Small: 10% | Large: 40%, Mid: 35%, Small: 25% |
Fund Beta attracts attention with its high headline return, but the details reveal trade-offs. Its volatility is significantly higher, minimum rolling return is negative, and expense ratio consumes over two percentage points of return annually. The fund manager has short tenure, the portfolio is highly concentrated, and turnover suggests frequent trading. While it may outperform in strong mid-cap rallies, it carries elevated risk — unsuitable for investors seeking steady compounding.
Fund Alpha, though more modest in returns, demonstrates consistency, lower risk, experienced management, and reasonable costs. Its diversified market-cap allocation aligns with a balanced ELSS mandate, and low turnover indicates a buy-and-hold discipline. For most ELSS investors — especially those using SIPs for goals like retirement or education — Fund Alpha offers a more reliable path to wealth creation.
Remember: ELSS is not about picking the top performer of the year. It’s about selecting a fund that can stay the course, manage risk prudently, and deliver inflation-beating returns over the long term. Use this framework to look beyond rankings and build a tax-saving investment that truly works for your future.
Step 1: Define Your Goal and Investment Horizon
Begin by clarifying why you are investing in ELSS. While tax savings under Section 80C is a primary motivator, ELSS is fundamentally an equity-linked instrument designed for long-term wealth creation. The mandatory three-year lock-in per SIP installment aligns best with goals that are at least three to five years away, such as a down payment on a house, funding higher education, or building a retirement corpus.
For example, if you are 30 years old and planning to buy a home in seven years, ELSS can serve as a growth-oriented component of your savings plan. The equity exposure has the potential to outpace inflation over this period, whereas traditional fixed-income options like PPF or tax-saving FDs may not. Conversely, if your goal is less than three years away — say, saving for a vacation next year — ELSS is unsuitable due to market volatility and the lock-in constraint. In such cases, liquid or ultra-short-term debt funds are more appropriate.
Write down your goal, the target amount, and the time horizon. This transforms a vague intention like “save tax and grow money” into a concrete plan: “Invest ₹12,500 per month in ELSS for five years to accumulate ₹10 lakhs for a home down payment.” This clarity helps you stay committed during market fluctuations and choose the right fund based on risk tolerance and horizon.
Step 2: Complete KYC and Open Your Investment Account
Before investing, you must complete the Know Your Customer (KYC) process, a one-time mandatory requirement for all mutual fund investments in India. KYC verifies your identity and address using documents such as your PAN card, Aadhaar, passport, or voter ID, along with a recent photograph.
You can complete KYC online through any SEBI-registered KRA (KYC Registration Agency) portal like CVL KRA, NSDL, or CAMS. The process typically takes 1–2 business days if your documents are clear and Aadhaar-linked. Once KYC is done, it is valid across all fund houses and platforms — you do not need to repeat it for every new investment.
Next, choose where to invest. You have three main options:
- Directly with the fund house: Visit the AMC’s website (e.g., SBI Mutual Fund, ICICI Prudential) and invest in their direct plans. These have lower expense ratios since there is no distributor commission.
- Through a registered investment advisor (RIA): If you want personalized advice, an RIA can help you select funds and build a portfolio. They charge a fee but do not earn commissions, reducing conflict of interest.
- Via a digital platform or distributor: Apps like Zerodha Coin, Groww, Paytm Money, or ET Money offer user-friendly interfaces to invest in direct or regular plans. Ensure the platform is SEBI-registered and offers access to direct plans to minimize costs.
For instance, Priya, a 28-year-old software engineer, completes her KYC on the CAMS portal using her PAN and Aadhaar. Within 24 hours, her status shows “KYC Verified.” She then opens an account on Zerodha Coin, links her bank account, and begins browsing ELSS funds in the direct plan section to avoid extra charges.
Step 3: Select an ELSS Fund Using the Evaluation Framework
Apply the framework from the previous section to choose a fund that matches your goal and risk profile. Do not rely solely on past returns or star ratings. Instead, evaluate consistency, risk-adjusted performance, cost, and management quality.
Suppose you are investing for a seven-year goal and prefer a balanced approach. You shortlist two funds based on the criteria discussed:
| Criteria | Fund Gamma | Fund Delta |
|---|---|---|
| 5-Year CAGR | 12.8% | 15.3% |
| 3-Year Min Rolling Return | 5.2% | -2.0% |
| Standard Deviation (3Y) | 14.1% | 20.7% |
| Sharpe Ratio (3Y) | 0.62 | 0.41 |
| Expense Ratio | 0.85% | 2.00% |
| Fund Manager Tenure | 9 years | 3 years |
| Top 5 Holdings | 35% of AUM | 58% of AUM |
| Portfolio Turnover | 38% | 82% |
| AUM | ₹6,500 crore | ₹2,100 crore |
| Market-Cap Allocation | Large: 60%, Mid: 30%, Small: 10% | Large: 35%, Mid: 40%, Small: 25% |
Fund Delta shows higher returns but comes with significantly higher volatility, a negative minimum rolling return, high expense ratio, short manager tenure, and concentrated holdings. Its high turnover suggests frequent trading, increasing costs and potential for style drift.
Fund Gamma, while offering lower headline returns, demonstrates consistency (positive minimum rolling return), lower risk, experienced management, lower costs, and disciplined turnover. Its market-cap allocation reflects a balanced approach suitable for a medium-to-long-term horizon.
For a goal like your child’s education in seven years, Fund Gamma is the more prudent choice. It aims to deliver steady compounding without exposing you to unnecessary drawdowns. Remember, ELSS is a long-term wealth-building tool — not a lottery ticket. Prioritize funds that can stay the course across market cycles.
Step 4: Start SIP, Automate, Review Annually, and Renew After Lock-in
Once you’ve selected a fund, set up a Systematic Investment Plan (SIP). Decide on a monthly amount based on your goal and cash flow. For example, to accumulate ₹15 lakhs in 10 years assuming an average annual return of 12%, you would need to invest approximately ₹7,000 per month. Use an SIP calculator to adjust for your specific target and horizon.
Instruct your bank to auto-debit the SIP amount on a fixed date each month — ideally shortly after your salary is credited. This ensures discipline and leverages rupee-cost averaging: you buy more units when NAV is low and fewer when it’s high, reducing the impact of market timing.
After each SIP installment, the three-year lock-in begins individually. For instance, if you start an SIP in April 2024, the April 2024 installment locks in until April 2027, the May 2024 installment until May 2027, and so on. You cannot redeem or switch these units until their respective lock-in periods end. However, you can continue the SIP beyond three years — and you should, to benefit from compounding.
Review your ELSS investment annually, not to chase returns, but to ensure the fund still aligns with your goal and risk tolerance. Check for:
- Changes in fund manager or investment process
- Significant shifts in portfolio concentration or sector allocation
- Sustained underperformance relative to peers and benchmarks over 2–3 years
If the fund’s fundamentals remain sound, stay invested. Avoid reacting to short-term volatility. For example, if Fund Gamma’s Sharpe ratio dips temporarily from 0.62 to 0.50 during a market correction but its process and holdings remain stable, there is no need to exit.
After the first three years, your earliest SIP installments become eligible for redemption. At that point, you can choose to:
- Redeem the unlocked units if you need the funds for your goal
- Keep them invested to continue compounding
- Start a new SIP in another ELSS fund if you wish to diversify across fund houses
For instance, after three years, Aarav redeems the units from his first year of SIP to make a down payment on a house, while continuing his SIP for future goals. This staggered approach turns ELSS into a flexible, long-term savings engine.
Try This: Your First Steps This Week
Take action now to begin your ELSS journey:
- Define one specific goal: Write down a financial objective that is at least three years away (e.g., “Save ₹8 lakhs for a home down payment in five years”) and calculate the monthly SIP needed using an online SIP calculator.
- Check your KYC status: Visit a KRA portal like CVL KRA or NSDL and enter your PAN to see if you are already KYC-compliant. If not, initiate the e-KYC process using your Aadhaar.
- Research one ELSS fund: Go to a fund house website or platform like Moneycontrol or Value Research, pick an ELSS fund, and review its factsheet for manager tenure, expense ratio, portfolio turnover, and 3-year minimum rolling return.
Key Takeaways
- ELSS combines tax savings under Section 80C with long-term wealth creation through equity exposure, making it ideal for goals three years or more away.
- Success in ELSS investing depends on discipline: define clear goals, complete KYC, choose a fund using a rigorous framework, automate SIPs, and review annually without reacting to market noise.
- The three-year lock-in applies per SIP installment, so continue investing beyond the initial period to build a growing corpus and benefit from compounding over time.